Wednesday, January 20, 2016

Springtime is Coming!!

It is almost that time!
Spring is coming- when birds are chirping, weather is warming, bees are buzzing...

When flowers are blooming, and house sales are BOOMING!

Don't be caught unprepared!  If you are hoping to move this year, now is the time to prepare your home for sale.  I have sold my last four listings to the FIRST person who saw the home. And they all sold within 4 days of listing!

HOW?  With careful planning and preparing!  I offer quite a few services that the average agent does not.  If you are ready to buy or sell, give me a call or shoot me a text today.  I will visit your home, and leave you with a list of to-do items which will not only allow your home to sell quickly, but to sell for top dollar.

Don't call your mom's best friend's hairdresser's daughter's roommate, just because she has a license.  Call me, and let's get your home SOLD!


Monday, June 29, 2015

About Me

Thank you for visiting!

I have a story that is a bit unusual from most other Realtors!

I began my career in the home warranty industry.  Realtors were actually my clients!  I sold warranties to them and to home buyers, and that allowed me to learn about home systems and compliances.  After doing that for a couple of years, I was asked to join a mortgage company.  I once again found myself selling mortgages and our services to both realtors and to home buyers.  This job was invaluable to my current career!  I was able to work through the entire back end of the home buying process.  I saw every step from mortgage application through to the closing.  I gained understanding of qualification issues, lending statutes, and bank regulations as well.  I also became familiar with many of the most popular loans used today.

I became even more intrigued by the "other side" of real estate.  I obtained my real estate license, and 3 years later, became a broker and opened my own office!  Today, I have multiple real estate agents working in my firm, Vineyard Real Estate Group.  Our agents are the best of the best!  We have agents who specialize in everything from residential to commercial to property management... even short sales and HUD homes!

If you have real estate questions, I'm certain we have your answers!
We are anxious to hear from you!

Sunday, June 14, 2015

Marietta: 92 acres almost assembled for new businesses- via Atlanta Business Chronicle

Marietta, Ga., is close to assembling 92 acres of city-owned property on Franklin Road by buying and tearing down apartment buildings. Leaders hope the land will attract new development.
The site is less than 10 miles from the Braves new Cobb County home in the Cumberland area. The team's move to Cobb County is credited with sparking more interest in Marietta's Franklin Road area and other nearby areas.
The Marietta City Council moved closer Wednesday night to purchasing the 28-acre 400-unit Marquis Place apartment complex on Franklin Road for $17.3 million, the Marietta Daily Journal reports.

Atlanta home sales gain, prices surge! - from Atlanta Business Chronicle

The dollar volume of Atlanta residential real estate sold continued its torrid pace in May with another double-digit gain from the previous year, while growth in the number of home sales remained sluggish with a 3 percent increase from May 2014, according to Atlanta-based Beacham and Co.
According to the local MLS, there were 5,130 home sales in the five-county metro (Cobb, DeKalb, Forsyth, Fulton and Gwinnett) last month compared to 4,949 a year ago, or a difference of 181 sales. Total dollar volume sold was another story. The combined sales price of all homes sold increased from nearly $1.4 billion to more than $1.5 billion. Both homes sold and dollar volume sold figures include sales of single-family detached homes as well as condos and townhomes.
The average home sales price increased 6.6 percent in May to $300,410 from $281,880. It is believed to be the first time ever that the average home sales price in Atlanta exceeded $300,000. Home prices typically peak in June or July every year, Beacham and Co. reported.
The number of home sales in Buckhead increased 11.8 percent in May. There were 218 home sales in Buckhead compared to 195 a year ago. The average sales price of single-family detached home sales in Buckhead was $1,067,838 last month compared to $949,321 a year ago, or a difference of 12.5 percent.
Sales of luxury properties were particularly strong in May, although the average sales price declined. There were 15 sales of $2 million or more in May compared to 10 in May 2014. The average sales price last month was $2,996,012 compared to $3,217,000 in May 2014, or a decline of 6.9 percent.

Fewer Atlanta Homeowners Underwater -from bizjournals.com

The U.S. negative equity rate is dropping, but 43.1 percent of Atlanta homeowners with a mortgage are still effectively underwater, according to the first quarter Zillow Negative Equity Report.
Seattle-based Zillow Inc. (NASDAQ: Z) reported Atlanta’s negative equity rate dropped to 23.2 percent in the first quarter from 26.1 percent in the fourth quarter of 2014. This was the biggest quarter over quarter improvement in negative equity of the 35 metros included in the analysis. A year ago, the rate was 33.6 percent.
At the end of the first quarter, the cumulative amount of negative equity in the metro area is $15.858 billion.
Spring and summer are the busiest buying and selling seasons, and this year, there is high demand for homes in the bottom third of the market. However, a disproportionate number of those homeowners are simply stuck in their homes and can’t afford to sell to buyers looking for homes in their price range.
The rate of underwater homeowners is much higher among the homes with the least value. In Atlanta, 46. percent of homes in the bottom third are in negative equity, compared with 20.2 percent in the middle third, and 10.1 percent in the top third.
“It’s great news that the level of negative equity is falling, but what really worries me is the depth of negative equity. Millions of Americans are so far underwater, it’s likely they may not re-gain equity for up to a decade or more at these rates,” Zillow Chief Economist Dr. Stan Humphries said in a statement. “And because negative equity is concentrated so heavily at the lower end, it throws a real wrench in the traditional housing market conveyor belt. Potential first-time buyers have difficulty finding affordable homes for sale because those homes are stuck in negative equity. And owners of those homes can’t move up the chain because they’re stuck underwater in the entry-level home they bought years ago. The logjam at the bottom is having ripple effects throughout the market, and as home value growth slows, it will be years before it gets cleared up. In the meantime, we’ll be left with volatile prices, limited inventory, tepid demand, elevated foreclosures and a whole lot of frustration.”
Among the 35 largest housing markets, Las Vegas, Chicago and Atlanta had the highest rates of homeowners in negative equity.

Banks annihilating "zombie foreclosures" - from CNBC

They are a blight on neighborhoods and bank balance sheets: homes in the foreclosure process, some in limbo for several years, their former owners gone but the home still not repossessed by the bank. They were dubbed "zombies" because their empty state was seen as a danger to both the neighborhood and the overall health of the housing market. 
Banks had let these homes sit because they were of so little value and because of endless foreclosure processing issues. Most are in disrepair, some occupied by squatters or drug dealers. But now, things are changing. The legal process has been largely streamlined, and as home prices rise nationwide, so too do the values of these zombie homes; banks are now pushing them through the foreclosure process and out to auction far more quickly. 
Foreclosure house
Marcelo Piotti | Getty Images
There are now about 127,000 zombie foreclosures, down 10 percent from a year ago, according to RealtyTrac, a foreclosure listing and analytics company. That means that one in five homes that are in the foreclosure process, that is the legal process has started but the bank has not yet repossessed the home, are vacant. 
Despite the overall drop, zombie foreclosures are rising in some of the highest-priced markets, such as Los Angeles, New York, Boston and Houston. That is because banks are moving the process more quickly in order to take advantage of rising home prices; so former owners are finally moving out. When the house is vacant, it becomes a zombie. 
"They've been able to stay in that home and maybe fight foreclosure for three, four, five years, and now finally the bank is coming back with all their ducks in a row, the proper documentation, and the homeowner is seeing the writing on the wall that I'm going to have to leave and move on with my life," said RealtyTrac Vice President Daren Blomquist. 
In just the last two months, banks have really ramped up on repossessing homes. These so-called REOs (bank repossessions) are now at a 17-month high. This, as the value of these former zombies rises amid strong housing demand and tight housing supply. 
"The average price of a zombie foreclosure nationwide was $195,000, so we're not talking about just $20,000 or $30,000 properties here," added Blomquist. 
That is good news to neighbors, like Ariel Seeley, who recently moved into a transitional Washington, D.C., neighborhood with her young family.
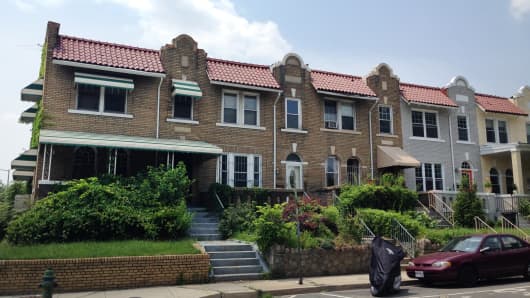
The end unit is a foreclosed, vacant home in Washington, DC's Petworth neighborhood.  RealtyTrac estimates its value at $600,117.
Stephanie Dhue | CNBC
The end unit is a foreclosed, vacant home in Washington, DC's Petworth neighborhood. RealtyTrac estimates its value at $600,117.
"For us as neighbors, we'd love to have people move in and occupy the houses," Seeley said. "It makes it seem a little unsafe or dreary when you're walking by and you see vacant signs, and you don't know what's going on with the houses." 
The phenomenon, however, like all real estate, is very local. While some areas are seeing the zombies annihilated—moved to auction and final sale—quickly, others are not. 
"In Chicago, you've got a real variation within the city among markets. You see stronger neighborhoods where prices have gone up steadily, and those areas are not where the zombie foreclosures are located," said Geoff Smith, executive director of the Institute for Housing Studies at DePaul University. "There are neighborhoods that continue to struggle, and those price levels are still well below where they were at the peak or even in 2000." 
Banks are honing in on foreclosures in stronger local markets, but there is a cost to completing a foreclosure and a cost to selling the property, and in some areas there is not necessarily a market that would bear these costs. In those cases, the vacant homes sit longer and continue to be a blight on the neighborhood. 
—CNBC producer Stephanie Dhue contributed to this report.

Buyers Scramble to Buy Homes as Interest Rates Increase - from CNBC

The interest rate sharp jump to the highest level this year caused a sudden surge in mortgage applications. While that may seem counter-intuitive, there's a reason: fear that rates will move even higher.  
Total mortgage application volume jumped 8.4 percent on a seasonally adjusted basis last week from the previous week, according to the Mortgage Bankers Association. The previous week included an adjustment for the Memorial Day holiday.
"Mortgage application volume rebounded strongly … indicating that the holiday had a larger impact on business activity than originally assumed," said Mike Fratantoni, the association's chief economist.
Refinance volume increased 7 percent on the week, and applications to purchase a home jumped 10 percent, both seasonally adjusted. Purchase volume is now 15 percent higher than the same week one year ago, but refinance volume is off nearly 5 percent. The weekly move higher in refinances was likely due to the holiday skewing the trend. Refinances are still lower than they were two weeks ago. This all comes as rates continue to climb.
The average contract interest rate for 30-year fixed-rate mortgages with conforming loan balances ($417,000 or less) increased to 4.17 percent, its highest level since November, from 4.02 percent, with points increasing to 0.38 from 0.33 (including the origination fee) for 80 percent loan-to-value ratio loans, according to the association. 
While higher rates make home buying more expensive, sharp moves higher often have the immediate effect of getting potential buyers off the fence, before chilling the overall market in the longer term. That is especially true now, in light of rising bond yields and the Federal Reserve's expected interest-rate hike.
"These increases really help the home-buying market. It really gets buyers to really understand that 'wait a minute, rates are at an all-time low, let's react now, let's react before they go higher,'" said Matt Weaver of Florida-based PMAC Lending.
Weaver said last week that he had a rush of clients calling in to lock-in rates. That was probably smart, as rates continued their move higher in yet another bond market sell-off. Both the spike in foreign bond yields as well as strong U.S. economic data point to an upward trajectory for interest rates, at least in the short term.
While the surge in purchase applications would seem to be welcome news, especially as the usually busy spring market draws to a close, some analysts warn the picture is not as rosy as it looks. 
"We think the excitement is misplaced," analysts at Goldman Sachs said in a note to investors Tuesday. "This index [mortgage bankers' purchase application index] has been largely range-bound since 2010. Even after the recent increases, it is still at levels comparable to 1996 when the size of the population and housing stock were 15 percent smaller." 
Mortgages
30 yr fixed4.09%4.18%
30 yr fixed jumbo4.33%4.45%
15 yr fixed3.21%3.37%
15 yr fixed jumbo3.80%4.01%
5/1 ARM3.38%5.48%
5/1 jumbo ARM3.44%5.97%
Find personalized rates:

Monday, June 21, 2010

4430 Wimberly Way, Cumming, GA | Powered by Postlets

4430 Wimberly Way, Cumming, GA Powered by Postlets
Click above to view my latest listing!

June 16th Update!

Today, the Senate passed an extension to the tax credit. However, the credit provision is part of a larger jobs and tax package that both chambers must still vote on before it becomes law. This extension, if passed, would allow only those individuals who already have signed contracts to complete the transaction after June 30th. More information will be passed along as Congress works on this extension.


~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~

WASHINGTON — The Senate on Wednesday approved a plan to give home buyers an extra three months to finish qualifying for federal tax incentives that boosted home sales this spring. The move by Senate Majority Leader Harry Reid would give buyers until Sept. 30 to complete their purchases and qualify for tax credits of up to $8,000. Under the current terms, buyers had until April 30 to get a signed sales contract and until June 30 to complete the sale. The proposal, approved by a 60-37 vote, would only allow people who already have signed contracts to finish at the later date. About 180,000 homebuyers who already signed purchase agreements would otherwise miss the deadline.

Reid, D-Nev., added the proposal to a bill extending jobless benefits through the end of November. Nevada has the nation's highest foreclosure rate, and Reid is facing a tough re-election campaign. The Realtors group has been pushing hard in Congress for the extension. Mortgage lenders, the trade group says, have been swamped with borrowers trying to get approved by the end of the month. Many potential borrowers are unlikely to make the deadline. "If Congress fails to act promptly, then prospective homebuyers might not get the benefit of the homebuyer tax credit, even though they have completed contracts," the Realtors said in a letter to lawmakers.

First-time buyers were eligible for a tax credit of up to $8,000. Current owners who bought and moved into another home could qualify for a credit of up to $6,500. The $140 million cost of the measure would be financed by denying businesses the ability to deduct from their taxes punitive damages paid when losing lawsuits or judgments.

The information above was provided by James A Williamson of Fairfield Mortgage.

May 26th Update!

Mortgage Rates Plummet


Just when everyone seems to be predicting that mortgage rates will rise, out of the blue they have dropped to the low point of the year! This remarkable development has occurred for the following three reasons:

1. Global economic concerns. The trouble in Europe continues to brew and threatens to spread as European countries are forced to reduce government spending. In addition, Chinese officials are now focused on tightening monetary policy to reduce inflation. Also, tensions between North Korea and South Korea continue to build. Investors have reacted to these crises by shifting money to relatively safer assets such as bonds and U.S. mortgage-backed securities (MBS) and this has had the effect of pushing mortgage rates lower.

2. Domestic economic uncertainty. In the U.S., it's not clear to what degree a newly proposed financial regulation bill will cause banks to reduce lending and lead to slower economic growth. In response to periods of uncertainty such as this, investors seek to reduce risk by moving to safer assets which, again, has led to lower rates.

3. Tame inflation. April Core CPI inflation fell to the lowest level in 44 years!! Low inflation always equates to low rates.


Mostly Positive Economic Data

On the housing front, recent news has been mostly positive. March Pending Home Sales increased 5.3% from February and were 21% higher than one year ago at this time. April Housing Starts increased above the consensus forecast to the highest level since October 2008. In addition, the May NAHB Homebuilder confidence index rose to the highest level since August 2007. Although the number of builder permits declined moderately, builders surveyed remained optimistic about sales over the next six months even as the home buyer tax credit expired.

More good news to report as retail sales rose for 7th straight month and oil prices fell to $65 per barrel reaching the lowest level since July 2009. The correlation between oil prices and mortgage rates is staggering!

On the jobs front, the weekly jobless claims unexpectedly jumped well above the consensus forecast and this figure will be closely watched over the next few weeks.

Flood Insurance Program Set to Expire

The National Flood Insurance Program is set to expire on May 31st. By law, a lender has to check to see if a property is in a flood zone before a mortgage can close. If the flood cert comes back negative (as most in Atlanta area do), there isn't an issue. However, if it comes back positive, the appropriate flood insurance coverage must be obtained prior to closing. If Congress does not address this issue and extend the program this week (they are not in session next week), the program will expire for the third time this year! This means that any loan closings scheduled that do not have the required flood insurance arranged by Friday will have to be delayed. Just what we need in this market! Congress has allowed this issue to linger for months and one existing proposal only would extend the program through Dec 31. Our elected officials need to figure this one out and quick or there are going to be some serious repercussions to anyone wanting to buy a house who needs flood insurance.


Rate Update

Mortgage rates have reached the lowest point since early December of 2009!

Looking Ahead

The last half of this week will be busy with New Home Sales and Durable Orders figures being released today. Also, a revised figure for first quarter Gross Domestic Product (GDP) will be released tomorrow and the Chicago PMI Manufacturing Index and Personal Income on Friday. Consumer Sentiment and Consumer Confidence round out the busy week.

All information above was provied by James A Williamson of Fairfield Mortgage

Sunday, May 16, 2010

Real Estate Update, May 16th 2010

Greek Troubles Overshadow Strong Data


Last week, the global financial markets remained focused on the economic troubles of Greece. Greek workers responded to proposed austerity measures with strikes and riots, and investors grew increasingly concerned that other smaller European countries will face similar problems cutting their budget deficits. As a result, US mortgage markets were helped in two primary ways:

1. Investors sought a flight to quality and shifted funds to safer investments, including US Treasuries and mortgage-backed securities (MBS).

2. Continued economic turmoil in Europe will reduce US exports to the region, which will slow US economic growth and reduce inflationary pressures.

Increased demand for MBS and lower future inflation are both positive for mortgage markets and contributed to keeping mortgage rates low over the last week.

Strong April Employment Report

Last week's April Employment report exceeded expectations in nearly every area. Against a consensus forecast of 190K, the economy added 290K jobs in April, the most since March 2006! In addition, the data from prior months was revised higher by an additional 121K. The manufacturing sector also added the most jobs since 1998! The Unemployment Rate rose to 9.9% from 9.7%, but that was due to unexpectedly large growth in the labor force as more people began to seek jobs.


The Fed Stays the Course

The recent Federal Open Market Committee ended without any major changes. The Fed kept the Fed Funds Rate the same and made no change to their Policy Statement, stating that rates will remain low for an "extended period" of time. Although the Fed does not directly control residential mortgage rates, there are presently three major threats to low rates lurking out there that do relate to the Fed:

1. The Fed made no mention in their latest Policy Statement about selling any of their Mortgage Backed Security (MBS) holdings. However, minutes from the meeting will be released at a future date and if the Fed discussed this topic at the meeting, it could cause rates to rise.

2. There is growing concern that if the Fed doesn't begin selling some of their MBS holdings by 2011, additional asset bubbles may arise. It's likely that the Fed will look to sell a meaningful chunk before year-end and, when this does happen, there stands to be some upward pressure on rates at that time.

3. Despite a stronger Stock market, higher consumer confidence, and an improved housing market, St. Louis Fed President Thomas Hoenig remains the lone dissenter to the verbiage in the Policy Statement regarding keeping rates low for an "extended period." He feels that there is a strong risk of inflation ahead and that the Fed needs to prepare the markets for the eventual hikes that will be coming to the Fed Funds Rate. When other Fed members agree with Hoenig (and the day will come), this verbiage will change and this will be a signal that the Fed now considers inflation to be a real threat. Since inflation is the archenemy of mortgage rates, the change in verbiage will cause rates to move higher.

Sunday, January 31, 2010

Foreclosures and REO's

Are you interested in pursuing a Foreclosures or REO home?
Here are some facts to review:

What is Foreclosure?
Foreclosure is a process that allows a lender to recover the amount owed on a defaulted loan by selling or taking ownership (repossession) of the property securing the loan. The foreclosure process begins when a borrower/owner defaults on loan payments (usually mortgage payments) and the lender files a public default notice, called a Notice of Default or Lis Pendens. The foreclosure process can end one of four ways:
The borrower/owner reinstates the loan by paying off the default amount during a grace period determined by state law. This grace period is also known as pre-foreclosure.
The borrower/owner sells the property to a third party during the pre-foreclosure period. The sale allows the borrower/owner to pay off the loan and avoid having a foreclosure on his or her credit history.
A third party buys the property at a public auction at the end of the pre-foreclosure period.
The lender takes ownership of the property, usually with the intent to re-sell it on the open market. The lender can take ownership either through an agreement with the borrower/owner during pre-foreclosure, via a short sale foreclosure or by buying back the property at the public auction. Properties repossessed by the lender are also known as bank-owned or REO properties (Real Estate Owned by the lender).

January 19th Update

RESPA Changes / The New Good Faith EstimateThe new Good Faith Estimate (GFE) became effective on January 1 and is the centerpiece of the RESPA changes. The form is now standardized and the same from lender to lender and this consistency is a good thing. However, the form has gone from 1 to 3 pages and is now flat out too long. Here is everything you need to know about page 1 of the new form:


The form begins innocently enough with "Borrower / Lender info” and “Purpose” sections at the top. However, the next “Shopping for your loan” section encourages the borrower right off the bat to do a lot of shopping with the insinuation that it is all about price and not service. In fact, this is one of the main themes of the new form. With this said, the realtor’s job will be more important than ever to emphasize that it really is about service first, and then price.
The next section is entitled “Important dates” and there are four dates or timeframes listed. This is a very cumbersome section and just too much info. The most important thing shown in this section is that the GFE must be valid for at least 10 business days. If the GFE is not accepted within 10 days, then the Loan Officer is no longer bound by the GFE. Once the borrower accepts the GFE, however, the fees become binding and are subject to increase only if the borrower requests a change or there is a “change in circumstance.” If there is a valid change in circumstance (such as a change in the contract), then a new GFE has to be disclosed within 3 days of the change and at least 1 day prior to closing. Thus, it will be critical that the realtor notify the Loan Officer immediately if there are any changes that will cause fees to increase (Sales price, Seller paid costs, Closing date, etc.). Decreases are OK and do not necessitate a new GFE.


Also, it is important to be aware that lenders can no longer collect fees up-front from the borrower until the GFE has been accepted. The only exception to this rule is that a small fee can be collected for the Credit Report. A fee for the appraisal can’t be collected until after the GFE has not only been generated and given to the borrower, but also officially "accepted" by them. I understand that a lot of people have been taken advantage of in the past and that there is a lot of good in this rule; however, this is not good news for the Loan Officer who is trying to meet a contract deadline, collect the appraisal fee, and get the appraisal ordered. Because of this new system, it is going to take longer to get appraisals and approvals done, thus, the realtor needs to leave longer time frames for the appraisal and approval contingencies to be completed. I am suggesting 2 weeks for the Appraisal Contingency and 3 weeks for the Approval Contingency. It is also critical that the realtor get the final contract to the Loan Officer asap.
The next “Summary of your loan” section is good basic loan info that has not been on the form before. There are five "Yes / No" answers to key questions such as if the rate or payment can rise, if the loan has negative amortization, and if there is a prepayment penalty or balloon. This section is a good addition but the payment listed is very confusing. Note that it is the sum of the P&I and PMI. No one looks at the sum of P&I + PMI! The payment listed should be just the P&I or the total PITI.


The “Escrow account information” section indicates whether escrows are required. This is good to know but, again, only two inches down the form the P&I + PMI payment is listed a second time. What is the purpose of showing this sum a second time? Why would the total PITI not be shown here or, for that matter, anywhere on the form? Yes, believe it or not, the total PITI payment is not shown anywhere on the new GFE.


The last section is the “Summary of your settlement charges" and is a tally of just that. These exact same figures are tallied again on page 2, so I am not sure the reason for the redundancy. This calculation is completely out of place at the bottom of page 1. The biggest shortcoming of the new GFE is that it does not show the down payment, the earnest money deposit, the total funds to close, or the PITI anywhere on the form. How can you call it a GFE without these things? How is the borrower supposed to know how much money he needs to bring to the closing? Obviously, no one with any direct lending experience was consulted in the creation of this form!


Next week, we'll continue to look at the rest of the new GFE form.
Low Inflation and Strong Auctions Influence Rates Downward
After climbing .5% in December, mortgage rates have eased back down .25% during the first two weeks of January. This drop can primarily be attributed to low inflation and strong demand at recent Treasury auctions.


Although inflation continues to be a huge long-term concern due to the enormous level of government spending, it has not been a factor in the short-term as virtually all of the data in recent months has shown it to be low and not an issue. Last week, the Consumer Price Index (CPI), the most widely watched inflation indicator, showed that core inflation rose only 1.8% from one year ago. This is square in the Fed's 1 - 2% comfort zone and the Fed is forecasting continued low core inflation throughout 2010.


Another long-term concern for mortgage investors is that the vast increase in the supply of government debt will exceed the demand. However, this has not been an issue yet in 2010 as both foreign and domestic demand has remained strong for long-term US Treasuries. The risk that important buyers (like China) will exit still exists, but so far so good!


Learning to Repeat Key Disciplines

To be a successful sales person, one of the most important concepts you can learn is that of repeating a few key disciplines each day. Prospecting, database management, and good communication with clients in your current pipeline are all examples of key disciplines. To be successful in this area, the following three things must be in place:

1. Attitude. You must first have a proper mindset. If you are negative all of the time, then expect negative things to happen to you. If you hang around with naysayers all of the time, then expect that to rub off on you. A positive, optimistic, "can do anything" attitude is critical to long-term success.

2. Plan. Research and think through exactly what needs to get done to be successful in your job. Ask others who are successful in your field what they do. Do some soul searching and ask lots of questions. Then write down your plan of action and keep it somewhere where you will see it regularly.

3. Execute. Take action and follow the plan. Ask someone you know and trust to hold you accountable.

Here's a great question to ask yourself today: What is one new discipline that I need to do every day to increase my volume? Think it through and then make it happen!


How to Permanently Change an Incorrect Credit Score
The credit reporting industry continues to be a fairly sloppy business. It is very common for someone to have inaccuracies on their credit report. Sometimes the mistakes are so severe that it prevents them from obtaining a mortgage. What should someone do to permanently correct inaccuracies that show up on their credit report? The answer is that they need to make sure that they fix the mistake at the bureau level. A little more insight is needed to explain exactly what this means.


Mortgage lenders use credit reporting agencies to pull credit reports. These agencies are middle-man companies that organize the credit data into easy to read reports, and have customer service departments to help lenders ensure their client's credit in satisfactory for the purpose of obtaining a mortgage. These credit reporting agencies should not be confused with the three national credit bureaus where all of the consumer data is stored. The bureaus are like warehouses that store the data and the credit reporting agencies are like trucking companies that come and get the data and then deliver it to consumers via lenders.


When a consumer finds that they have incorrect information on their credit report, it is critical that they get this fixed at the bureau level. If they provide something to their lender that clears an item up for a particular loan, they most likely have cleared the item up at the credit reporting agency only. This is a one-time fix. The key to a permanent credit score change is to submit the correction to all three of the credit bureaus which can be contacted as follows:


• Equifax: (800) 685-1111 / www.equifax.com• Experian: (888) 397-3742 / www.experian.com• TransUnion: (800) 916-8800 / www.transunion.com
Rate Update Rates have had a good January and are about .25% lower than the beginning of the year.

Monday, January 11, 2010

Real Estate Update 1/11/2010

Market Update:
Unemployment Static at 10%Today's Employment Report indicated that the economy lost -85K jobs in December (significantly more than the -5K forecasted) and that the Unemployment Rate remained at 10.0%. A small revision to the November data showed a gain of 4K jobs, the first monthly increase since December 2007. The details of the report suggest that small businesses may be creating jobs more slowly than larger companies and that the manufacturing and constructions sectors continued to perform poorly.

Housing Update:
In the housing sector, November Pending Home Sales fell 16% from October, but the decline followed nine straight months of increases and November Pending Home Sales were 15% higher than one year ago. Pending home sales are a leading indicator of future housing market activity. Recent data has been heavily influenced by the timing of the home buyer tax credit, which was originally set to expire at the end of November. A surge of buyers attempting to purchase before the original deadline pulled demand forward. When the home buyer tax credit was expanded and extended to April 30, 2010, the time pressure was removed. Hopefully, we will have a surge in purchase business between now and the end of April which will generate some momentum that will carry us through the end of the year!

Mortgage Rate Update:
Mortgage Rates on the RiseIn case you checked out for the holidays and are just now checking back in, the final few weeks of December were not kind at all to mortgage rates. Heading into December, mortgage rates were close to record low levels, but a combination of the following factors has caused rates to push about .5% higher from early Dec to the present:
An improving economic outlook: aside from today's Employment and Pending Home Sales reports, most of the recent economic news has been good. Although this is good news for the economy, stronger than expected economic data and a stock market rally are negative for mortgage markets because it generally leads to higher inflation.
Government spending: the government already will need to issue an enormous amount of debt to pay for its spending, and it now looks more than likely that additional expenditures are on the way for job creation and health care bills. Higher yields are required to attract investors to purchase the extra debt, pushing up yields for competing investments such as mortgage-backed securities (MBS).

Fed uncertainty: the Fed is winding down its $1.25 trillion MBS purchase program which is causing great uncertainty as to the future demand for mortgage investments.
Rates spent much of 2009 below 5%. My crystal ball indicates that it is more realistic that rates will stay in the 5-6% range throughout most of 2010.

Identify Your Key Result Areas:
A key result area is something that is under your control that you must achieve to succeed at your job. It is a healthy exercise to identify your key result areas. Prospecting, closing a sale, and effective transaction management are good examples. Your weakest key result area sets the height at which you can use all your other skills and abilities. You can be exceptional in 6 of 7 key result areas, but your poor performance in the 7th area will hold you back and determine how much you achieve with all your other skills. This weakness will act as a drag on your effectiveness and be a constant source of friction and frustration.
It is common to avoid jobs and activities in the areas where you have performed poorly in the past. Instead of setting a goal and making a plan to improve in a particular area, most simply avoid that area altogether, which just makes the situation worse. Likewise, the better you become in a particular area, the more motivated you will be to perform that function, the less you will procrastinate, and the more determined you will be to get the job finished.
We all have weaknesses. The key is to identify what yours are, and then set a goal and make a plan to improve in your weak areas. It is reassuring to know that all business skills are learnable. As you get started in 2010, resolve to master all of your key result areas and then, truly, nothing can hold you back!

Excerpts from "Eat That Frog!" by Brian Tracy
New Technology that Tells You How to Increase Your Credit Score
So, your latest and greatest client, Joe Buyer, has just had his credit report pulled and his credit score is a 605 and 15 points below the 620 minimum score needed. In the past, it would have been complete guesswork to determine what Joe would need to do to bump up his score by 15+ points. However, a tool now exists that analyzes Joe's credit report and lets him know how much his credit score will increase if specific actions are taken. The process is as simple as the Loan Officer running Joe's credit report through some special software. Then, amazingly, the report indicates specific actions that can be taken to improve his score such as:
• a 15 point increase for moving a credit card balance from one credit card to another• a 20 point increase for simply paying a credit card balance down by $2000• a 25 point increase for paying off and closing a particular account

The coolest part of this technology is the "What-If Simulator" which allows the Loan Officer to run countless "what-if" scenarios through the software to see how much the score will change if specific actions are taken. Talk about invaluable information that can help you get a buyer to closing! It is important that you are aware of this technology and that you can recommend it when needed. It is also important that you work with a Loan Officer who understands this technology and knows how to use it. At Fairfield Mortgage, we understand and use this technology regularly. Let us know when we can help your client figure out what they need to do to increase their credit score and qualify for a mortgage.

Rate Update
Rates have been flat over the last few weeks but are up .5% over the last month.

Thank you to James Williamson with Fairfield Mortgage for providing these updates each month!

Tuesday, November 17, 2009

Mortgage Update for November 17th, 2009

Stock Market Up, Mortgage Rates Down

Several Fed officials spoke up last week indicating that a solid majority of Fed officials feel that the economy is still too fragile and the labor market is too weak to begin to raise rates. Fed Chief Bernanke joined the band wagon yesterday by assuring investors in a speech that the Fed intends to keep rates at low levels. Confirmation that rate hikes are a long way off has encouraged investors to purchase stocks and mortgage-backed securities (MBS), and both the stock and bond markets have had a great week as a result. In fact, since the first Fed official comments last Wednesday, mortgage rates have improved a little each day. The stock and bond markets normally move in opposite directions, so to have a week where they both have healthy gains is great news!

Also, worth noting, October Retail Sales rose 1.4%, above the consensus forecast of 0.9%. Retail Sales minus autos, however, increased by only 0.2%, which was well below expectations. Investors will be closely watching the level of spending by consumers during the holiday season to help determine the strength of the economy.


Two Important HUD Announcements

On January 1, 2010, HUD will require that mortgage lenders provide consumers with a new standard Good Faith Estimate (GFE) that clearly discloses key loan terms and closing costs. Closing agents will also be required to provide borrowers with a new HUD-1 Settlement Statement that clearly compares consumers' final and estimated costs. This much has been known for some time, but HUD announced last week that for the first four months of 2010, they have instructed regulators to exercise restraint in enforcing the new RESPA GFE and HUD-1 regulatory requirements for those lenders who have made a good faith effort to comply with RESPA's new requirements. As long as the lender is moving forward with an investment and commitment in technology, training, and quality control designed to comply with the new rule, then they now have until May 2010 to proceed with the new law.
In a second HUD announcement last week, we learned that FHA capital reserves have fallen well below the required minimum level of 2% of loans. Just two years ago, FHA accounted for less than 2% of all loans originated. However, over the last year FHA has become the star of the show and now accounts for over 25% of all new mortgage loans. This low capital ratio is due to FHA having a lot of bad loans on its books. FHA has already taken significant action to improve the quality of its portfolio by increasing the down payment to 3.5%, increasing mortgage insurance to 1.75% up-front and .55% per month, implementing new condo rules, implementing new appraisal rules similar to HVCC set to take effect in January, and requiring higher net worth requirements for lenders. With this said, there is going to be more political pressure on FHA to increase its capital reserves and we should all expect more FHA changes in the days ahead. Possible changes are a higher minimum credit score, an increased down payment to 5%, or higher mortgage insurance premiums.


Sales Tip

You will never be able to do everything you have to do. You will never be caught up. You will always be behind in some of your tasks and responsibilities. With so much to do, you have to pick and choose what you do each day. Your key to reaching high levels of performance and productivity is to develop the habit of tackling your biggest, most important task first each day. Prioritize your tasks and then identify the most important one. Learn to begin the task immediately without delay or procrastination. Be determined, focused, thorough, and finish the task completely before moving on to the next task. Knocking out your biggest task of the day first is a key to great success and happiness in life!

Credit Report Tips
Credit cards play a huge role in the calculation of one's credit score. Here are a few tips that you may not know:
• Carrying too many credit cards with balances can hurt a score as it indicates higher risk and over-extension. Action Point: Actively use only a few credit cards.
• The ratio of a credit card's balance to the credit limit is critical and, ideally, all balances would be at 30% of the limit or less. Thus, the higher the credit limit the better, and the lower the balance the better. Action Point: Increase your credit card limits and pay down the balances to 30% or less of the limit.
• Carrying a small balance and paying timely will lead to a higher score than carrying no balance at all, but closing an unused account with a zero balance usually does not increase a score. Action Point: Maintain a small balance on credit cards and never let the payment be more than 30 days late.

Friday, November 6, 2009

TAX CREDIT EXTENSION PASSED

Congress has approved an extension today of the home buyers tax credit, sending the bill to the White House for the President's signature.

The House voted 403-12 to pass the bill after the Senate unanimously approved the measure Wednesday night. The legislation continues a home buyers' tax credit and a measure allowing businesses to write off some of their losses incurred over the past two years.

House lawmakers voted to approve the measure more than a month after initially agreeing to a more modest extension of unemployment benefits. The home buyers' tax credit and business-tax measure were added in the Senate.

The bill extends an $8,000 first-time home buyers' tax credit that was set to expire at the end of this month. The credit will apply to all house contracts entered into before April 30, 2010, and closed by June 30. It creates a new $6,500 credit for existing property owners looking to sell their home and buy another during the same period of time. Both credits have income restrictions limiting their availability.

Monday, June 29, 2009

Mortgage Update- Monday, June 29, 2009

Mortgage Rates Drop

With major economic data, a Fed meeting, and large Treasury auctions on the schedule, last week was a busy week for mortgage markets. In the end, it was the Treasury auctions which had the greatest impact on rates. Much of the rise in interest rates we have seen over the last month was due to concern about the enormous supply of debt the government needs to issue to pay for all the stimulus programs. The question has been whether investors would require significantly higher yields to continue purchasing bonds. Strong demand from both domestic and foreign investors at these auctions eased those concerns for now and helped pushed mortgage rates lower last week.

As expected, on Wednesday the Fed made no change to the Fed Funds rate. Although investor expectations varied widely regarding the Fed's statement, the good news is that the statement revealed no significant shifts in policy. In particular, there was no change in the timing or the quantity of future MBS and Treasury purchases. In addition, the statement contained no discussion about exit strategies to eventually unwind Fed stimulus programs. Overall, the Fed simply held the course, and mortgage rates were nearly unchanged after the news.
In the housing sector, May Existing Home Sales rose 2.4%. It was the first time since September 2005 that Existing Home Sales increased for two months in a row. The inventory of unsold homes declined to a 9.6-month supply from a 10.1-month supply in April. A NAR survey revealed that 29% of sales were to first-time home buyers, helped by the $8,000 tax credit, low mortgage rates, and favorable affordability levels.
Federal Tax Credit Growing from $8000 to $15,000?
There has been a lot of talk about the proposed $15,000 federal tax credit but since we have not been able to confirm any details, we decided to call Johnny Isakson's office directly. One of our loan officers called and spoke to one of his aides and was told that the proposal was on hold until it could be attached to another bill as an amendment. The aide said that support was strong from both sides of the aisle and they expected it to pass easily. Hopefully, they'll find another bill to attach it to soon! This may come together in the end but it sure doesn't seem like its going to be anytime soon. In the meantime, the $8000 federal tax credit seems to be working! As we talk with people in the industry, it is clear that purchase business has certainly picked up and much of that is first-time home buyer business.

A Quick Lending Tip for Each Major Type of Loan
Conforming: The minimum down payment in metro-Atlanta area is 10%. If a borrower is putting between 10-20% down, they will need to pay PMI and their debt ratio will be limited to 41%. FHA: The minimum down payment is 3.5% but there is more flexibility with debt ratios as they are often allowed into the mid 40's. VA: The original 100% loan program is again THE best 100% loan program. If your buyer is a veteran and doesn't want to put much money down, VA is the way to go. There is no PMI at all. Instead a 2.15% "VA Funding Fee" is added to the sales price and, thus, financed into the loan. Jumbo: The gap on Jumbo rates has closed to only about 1% more than Conforming resulting in Jumbo programs once again being a viable alternative. But if sales price is in the low $600k's or less, the best way to structure the financing is by maxing out the first at the $417k Conforming limit and then tacking on a 2nd mortgage for the difference. 2nd mortgages are much more difficult to get these days but there are still some out there and available! This technique is called a Jumbo Blend and although there are many hurdles to make it over with this approach, it usually is the best way to go when you compare payments. Rate UpdateIt was a good week for rates:

Looking Ahead This week, the ever important Employment Report will come out on Friday. As usual, this data on the number of jobs, the Unemployment Rate, and wage inflation will be the most highly anticipated economic data of the month. Early estimates are for a loss of about 370K jobs in June. Before the Employment data, the Chicago PMI and ISM National Manufacturing Indexes will come out on Tuesday and Wednesday. Pending Home Sales, a leading indicator for the housing market, will be released on Wednesday. Consumer Confidence, Construction Spending, and Factory Orders will round out the schedule. Mortgage markets will be closed on Friday ahead of the July 4th holiday.

The information contained herein is believed to be accurate, however no representation or warranties are written or implied. All Rights Reserved.

Monday, June 8, 2009

June 8th, 2009 Update

RATES CONTINUE TO SOAR

Investors have been concerned for quite a while about the coming supply of new debt needed to pay for all the government stimulus programs. On top of that, the economic outlook has been improving sooner than expected. The combination of these two potentially inflationary developments pushed mortgage rates higher during the week.

The economic surprise last week came from the Employment report. Although the economy lost -345K jobs in May, it was far fewer than the consensus estimate for a loss of -525K jobs. The Unemployment Rate jumped to 9.4% from 8.9% in April. A surge in people entering the labor force was responsible for the unexpected increase in the Unemployment Rate. The labor market is typically one of the last areas to show improvement during an economic rebound, so signs of a turnaround are particularly significant.

Fed Chief Bernanke supported the notion that the recession would end this year. In testimony before Congress last week, Bernanke stated that he still expects the economy to move higher later this year, although it may take a while for growth to return to average levels. He looked ahead to measures needed once the economic crisis has passed, such as containing the budget deficit and reducing government control of markets. At this point, most investors believe that the Fed is not inclined to expand the mortgage-backed security (MBS) purchase program beyond its current level of $1.25 trillion, unless economic growth falls short of the Fed's outlook.

More evidence that the economy may be rebounding came from last week's housing data. April Pending Home Sales rose for the third consecutive month, increasing 7% from March. Pending Home Sales are a leading indicator, meaning that future New and Existing Home Sales reports may show increases.


Looking Ahead

This week, the most significant economic data will be the Retail Sales report on Thursday. Retail Sales account for about 70% of economic activity. In addition, the Trade Balance and the Fed's Beige Book will be released on Wednesday. Import Prices and Consumer Sentiment will come out on Friday. There will be large Treasury auctions on Tuesday, Wednesday, and Thursday as well.

Have a great week and when you think of financing, please think of Fairfield!

To unsubscribe, please notify me at
r.crozier@fairfieldmortgage.com. The information contained herein is believed to be accurate, however no representation or warranties are written or implied. All Rights Reserved.

Monday, May 4, 2009

May 4th, 2009- Mortgage Update

News From Last Week

It was a busy week last week in financial markets and mortgage rates rose following Wednesday's Fed announcement and ended the week higher for the first time in a few weeks. Demand for the $101 billion in last week's Treasury auctions was average, and foreign investors purchased a healthy 29% to 33% of each auction. The stock market ended the week with little change. Nearly all of the movement in mortgage rates during the week was related to the Fed meeting.

In anticipation of the announcement of favorable new Fed actions, mortgage rates actually moved lower early in the week. Some investors were looking for the Fed to expand its purchases of Treasury securities, which would be positive for mortgage rates. Those investors were disappointed, however, as the Fed announced no new initiatives. The Fed made no change in rates, holding the fed funds rate close to zero. According to the Fed, the economic outlook has "improved modestly" since the March 18 meeting. A lack of new Fed programs and confirmation of improved economic prospects pushed mortgage rates higher.

Overshadowed by the Fed meeting, an important report on first quarter Gross Domestic Product (GDP) presented data which supports the Fed's economic outlook. GDP fell -6.1%, which was significantly weaker than the consensus forecast. However, a breakdown of the GDP report reveals that the weak headline number for the first quarter may not be reflective of the current condition of the economy. GDP fell more than expected mainly due to declines in inventories and business investment. Consumer spending actually far exceeded expectations. If this trend continues, then businesses will have to begin to rebuild depleted inventories, lifting future economic activity.


Looking Ahead

The important Employment report will come out on Friday. As usual, this data on the number of jobs, the Unemployment Rate, and wage inflation will be the most highly anticipated economic data of the month. Early estimates are for a loss of about 620K jobs in April. Before the Employment Data, Pending Home Sales and Construction Spending will come out on Monday. Pending Home Sales is a leading indicator for the housing market. The ISM Services index will be released on Tuesday, while Productivity is scheduled for Thursday. There will be large Treasury auctions on Tuesday, Wednesday, and Thursday. The results of the government's stress tests for 19 large financial institutions will be released on Thursday.
Have a great week and when you think of financing, please think of Fairfield!